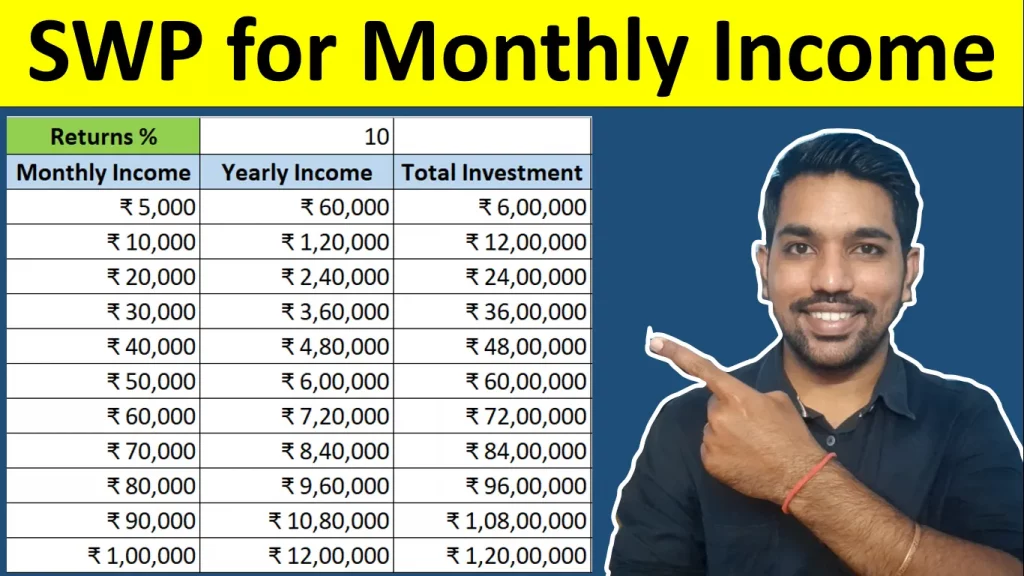
SWP for Monthly Income is a way to withdraw regular income from mutual funds in order to cover your expenses. The idea is to accumulate enough corpus in mutual fund of your choice, that will continue to perform better in future with good returns, and withdrawing from this mutual fund regularly (monthly frequency), to cover for the monthly expenses and thus replacing your source of income to cover those expenses. This is the best way to retire early and get regular income from mutual funds to enjoy post retirement life.
- SWP for Monthly Income Calculation Video
- What is SWP for Monthly Income from Mutual Funds?
- How SWP works with Example?
- Using SWP Calculator for Regular Income
- How Long Will Your Corpus Last?
- Is monthly income from SWP taxable?
- How much return is expected from SWP?
- Is SWP better than SIP?
- Is SWP better than FD?
- Conclusion
- Frequently Asked Questions
Let us understand more about SWP for Monthly Income in detail.
SWP for Monthly Income Calculation Video

Watch more Videos on YouTube Channel
So you get good returns as regular income with expected rate of 8% as seen in above video.
What is SWP for Monthly Income from Mutual Funds?
- SWP full form is Systematic Withdrawal Plan
- It helps you to get regular income from mutual fund, provided you have accumulated enough corpus in that mutual fund
- Similar to Post Office Monthly Income Scheme where you get fixed interest rate, the percentage of returns from mutual fund varies over time, but over long term you can get anywhere between 10% to 15% in good mutual funds
- You can also simply invest via SIP in Sensex to accumulate your target amount, and then systematically withdraw from this mutual fund
- Moreover, the regular income you earn from SWP can be used to cover your monthly expenses and hence you can retire from your salaried job and work for yourself in your own Life Goals
- SWP helps to retire early, provided you plan early in your life and start accumulating amount in a good mutual fund
ALSO READ: Income Tax on SIP Redemption in Mutual Funds
How SWP works with Example?
The working of SWP is quite simple:
- Let’s say for example you have accumulated Rs. 1 crore in a mutual fund that is expected to grow at 12% annually in upcoming years
- Which means 1% in every month will help you to get Rs. 1 Lakh profit in a month from Rs. 1 crore principal amount
- You need to choose a withdrawal amount based on your expenses, so let’s say your expenses is Rs. 50,000, and you choose to withdraw Rs. 60,000 to cover for unexpected expenses as well
So below is the table covering the withdrawal for first 6 months based on 12% expected returns:
| Month | Withdrawal per month | Returns Expected | Remaining Balance |
|---|---|---|---|
| 0 | – | – | ₹ 1,00,00,000 |
| 1 | Rs. 60,000 | 12% | ₹ 1,00,40,000 |
| 2 | Rs. 60,000 | 12% | ₹ 1,00,80,400 |
| 3 | Rs. 60,000 | 12% | ₹ 1,01,21,204 |
| 4 | Rs. 60,000 | 12% | ₹ 1,01,62,416 |
| 5 | Rs. 60,000 | 12% | ₹ 1,02,04,040 |
| 6 | Rs. 60,000 | 12% | ₹ 1,02,46,081 |
- Note that in above table you are withdrawing at the end of month after getting profits from mutual fund
- Since your withdrawal amount is less than the expected returns from the mutual fund, the remaining balance increases over time, which is a good sign
- Always try to keep your withdrawal amount below the expected returns so your balance doesn’t shrink over time
- The amount you withdraw every month can also be done manually and changed as per your requirements
Using SWP Calculator for Regular Income
You can also use below SWP calculator to calculate your monthly income from mutual funds based on your principal amount:
How Long Will Your Corpus Last?
The answer depends on how much you withdraw compared to what your corpus earns. Here’s how long Rs. 1 crore lasts at different monthly withdrawals, assuming a steady 8% annual return:
| Monthly Withdrawal | Yearly Withdrawal Rate | Corpus Lasts |
|---|---|---|
| Rs. 60,000 | 7.2% | Never runs out (balance grows) |
| Rs. 70,000 | 8.4% | About 38 years |
| Rs. 80,000 | 9.6% | About 22 years |
| Rs. 1,00,000 | 12% | About 14 years |
| Rs. 1,20,000 | 14.4% | About 10 years |
Corpus duration for Rs. 1 crore SWP at 8% assumed annual return. Real returns fluctuate, so treat this as a planning guide, not a guarantee.
A simple rule of thumb: keep your yearly withdrawal at or below your expected return, and your corpus should stay intact.
Is monthly income from SWP taxable?
Yes, but here’s the part many people miss: you don’t pay tax on the full amount you withdraw. Each SWP withdrawal is treated as selling some of your units, so only the profit portion of that withdrawal is taxable. The rest is just your own invested money coming back to you.
For equity mutual funds, as of FY 2025-26:
- Units held for more than 1 year (LTCG): Gains up to Rs. 1.25 lakh in a financial year are tax-free. Anything above that is taxed at 12.5%.
- Units held for less than 1 year (STCG): Gains are taxed at 20%.
For debt mutual funds, gains are added to your income and taxed at your slab rate.
Example: Say your units were bought at a NAV of Rs. 100 and are now worth Rs. 150. If you withdraw Rs. 60,000 in a month, one-third of that (Rs. 20,000) is profit and the rest is your original capital. Over 12 months, that’s Rs. 2.4 lakh of long-term gains. After the Rs. 1.25 lakh exemption, Rs. 1.15 lakh is taxable at 12.5%, which comes to roughly Rs. 14,950 including cess. That’s a tax of about 2.5% on your total Rs. 7.2 lakh of yearly withdrawals, which is why SWP can be quite tax-efficient compared to FD interest taxed at your full slab rate.
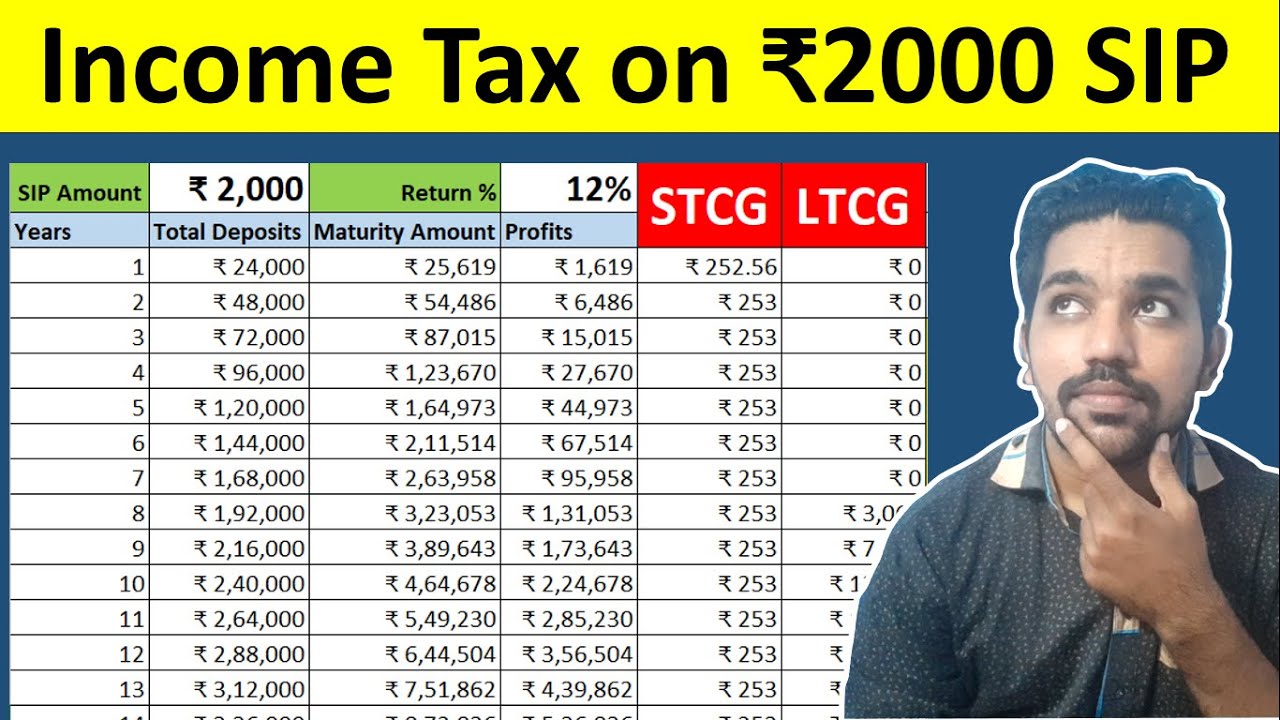
Watch below video on Income Tax on SIP Redemption to understand more about taxation on redemption:
How much return is expected from SWP?
Equity mutual funds have historically delivered somewhere around 10% to 12% over long periods of 10+ years, though this is not guaranteed. Some years will be negative, and others will be well above average. For planning your SWP, it’s safer to assume a conservative 8% to 10%, which is why the video above uses 8%.
There’s one risk worth understanding before you start: if markets fall sharply in the first few years of your SWP, you’re withdrawing from a shrinking corpus, and it may not fully recover even when markets bounce back. This is called sequence risk. Keeping 1 to 2 years of expenses in a liquid or debt fund as a buffer helps you avoid selling equity units at a bad time.
While making withdrawals via SWP, you can consider this average return on monthly basis and calculate your remaining balance as per your withdrawal. If your withdrawal amount is less than the actual profits you make in every month, the balance will increase. But if withdrawal is more than actual profits, the balance will decrease.
You should try to keep the balance increasing so that it does not get over with time and inflation.
Is SWP better than SIP?
SWP is the reverse of SIP. In SWP, you withdraw a specific amount every month from mutual fund to cover your monthly expenses, where as in SIP you deposit a specific amount in mutual fund to achieve a financial goal like accumulating wealth, children education, buying a house, etc.
The best combination will be to use both SIP and SWP. You can start SIP (Systematic Investment Plan) and slowly accumulate good amount in mutual fund, and once the accumulated amount helps you to cover your monthly expenses with the help of monthly profits, you can start SWP (Systematic Withdrawal Plan) to get regular income.
While starting SWP, ensure that the withdrawal amount is less than the expected profits that you make to keep the remaining balance increasing over time.
Is SWP better than FD?
FD or fixed deposits is used to achieve your short term or mid term goals, where as SWP is used withdraw from mutual funds to cover for expenses and it is a long term goal.
FD provides you low guaranteed returns in the range between 5% to 7% in a year with quarterly compounding where as SWP in mutual fund can provide returns between 10% to 15% in a year over long term.
So it depends on your goal tenure, for short term – FD or Fixed Deposits are better where as for long term and if you can take some risk in mutual funds, SWP is better.
Conclusion
So SWP or Systematic Withdrawal Plan helps you to withdraw regularly from mutual funds which can help you to cover for monthly expenses. It is better to withdraw monthly amount that is less than the profits you make in mutual funds on monthly basis to keep your balance increasing with time.
If your withdrawal amount every month is higher than the profits you make on balance, at one point of time your balance will become zero in which case you won’t be making any profits from mutual funds. So try to keep your withdrawal amount low compared to actual profits you make or are going to make in future.
Frequently Asked Questions
What is the full form of SWP?
SWP stands for Systematic Withdrawal Plan. It lets you withdraw a fixed amount from your mutual fund at regular intervals, usually monthly.
Is SWP safe?
SWP itself is just a withdrawal method, so its safety depends on the fund you’re invested in. Equity funds carry market risk, so your corpus value can fluctuate. Withdrawing less than the fund’s long-term returns, and keeping a buffer in a debt or liquid fund, reduces the risk of running out of money.
What is the best withdrawal rate for SWP?
Many planners suggest keeping your yearly withdrawal around 4% to 6% of your corpus if you want it to last 25+ years, especially after retirement. Higher rates work for shorter periods but increase the risk of depleting your corpus.
Can I change my SWP amount later?
Yes. You can increase, decrease, pause, or stop your SWP anytime through your mutual fund platform. Many investors increase the amount yearly to keep up with inflation.
Is SWP better than a dividend plan for regular income?
Generally yes. With SWP you control exactly how much you receive and when, and only the gains portion is taxed. Dividends are decided by the fund house, aren’t guaranteed, and are taxed at your slab rate.
Is SWP better than SIP?
They do opposite jobs. SIP builds your corpus while you’re earning, and SWP draws income from it later. Most people use SIP first and SWP after retirement or financial independence.
Some more Reading:
Save Home Loan Interest Amount!
Use Home Loan Excel Calculator that will help you to Save Interest Amount on Home Loan EMI.
Click below button to download Home Loan EMI and Prepayment Calculator in Excel:
Watch how Home Loan Calculator in Excel Works
Income Tax Calculator App – FinCalC
For Income Tax Calculation on your mobile device, you can Download my Android App “FinCalC” which I have developed for you to make your income tax calculation easy.
What you can do with this mobile App?
- Calculate Income Tax for FY 2025-26 and previous FY 2024-25
- Enter estimated Investments to check income tax with Old and New Tax Regime
- Save income tax details and track regularly
- Know how much to invest more to save income tax
- More calculators including PPF, SIP returns, Savings account interest and lot more
Use Popular Calculators:
- Income Tax Calculator
- Home Loan EMI Calculator
- SIP Calculator
- PPF Calculator
- HRA Calculator
- Step up SIP Calculator
- Savings Account Interest Calculator
- Lump sum Calculator
- FD Calculator
- RD Calculator
- Car Loan EMI Calculator
- Bike Loan EMI Calculator
- Sukanya Samriddhi Calculator
- Provident Fund Calculator
- Senior Citizen Savings Calculator
- NSC Calculator
- Monthly Income Scheme Calculator
- Mahila Samman Savings Calculator
- Systematic Withdrawal Calculator
- CAGR Calculator
I’d love to hear from you if you have any queries about Personal Finance and Money Management.
JOIN Telegram Group and stay updated with latest Personal Finance News and Topics.
Download our Free Android App – FinCalC to Calculate Income Tax and Interest on various small Saving Schemes in India including PPF, NSC, SIP and lot more.
Follow the Blog and Subscribe to YouTube Channel to stay updated about Personal Finance and Money Management topics.
Disclaimer: Mutual Fund investments are subject to market risks, read all scheme related documents carefully. Registration granted by AMFI, membership of SIRO (if applicable), and certification from NISM in no way guarantee performance of the intermediary or provide any assurance of returns to investors.
Distributor Details: Name: Abhilash Gupta | AMFI Registered Mutual Fund Distributor | ARN: 367014