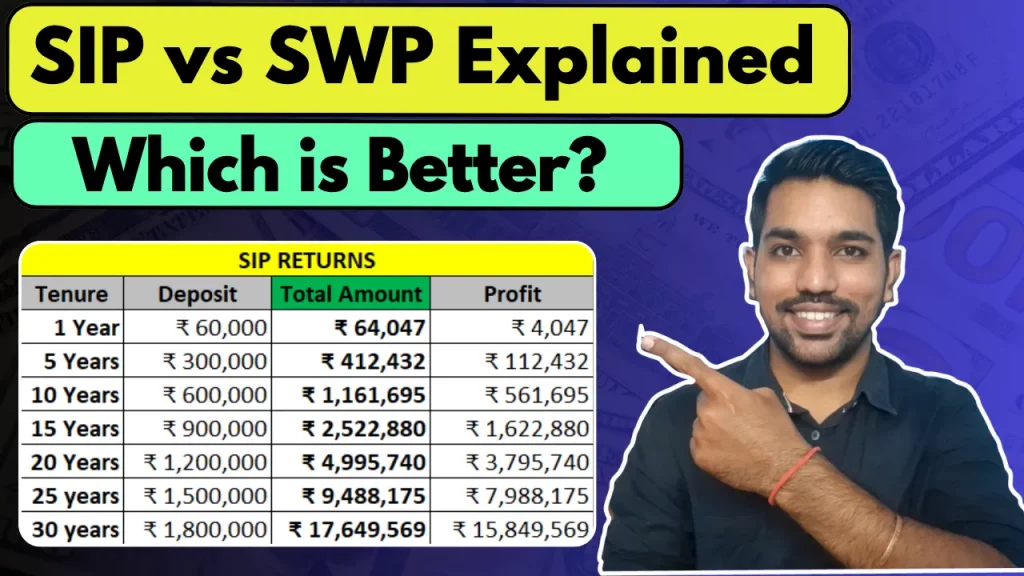
SIP and SWP are two important investment strategies that can help you to achieve financial independence and also retire early, commonly known as FIRE. SIP vs SWP is something that you should know if you want to lead a financially stable life with no stress. The full form of SIP is Systematic Investment Plan, that helps you to accumulate funds to achieve financial goals. SWP full form is Systematic Withdrawal Plan, that helps you in covering your regular expenses post retirement or during financial independence phase.
SIP and SWP together can work like a magic for you in your financial independence and early Retirement.
Let us understand SIP vs SWP in detail.
What is SIP?
- SIP full form is Systematic Investment Plan
- It is a way to invest in equity or mutual funds regularly every month to gradually move towards your financial goal
- SIP helps you to achieve goals such as buying a new house, new car, children’s education or getting early retirement
- Every month you can choose to invest any amount, starting from Rs. 500 and increase this amount at will every year
- The increment in SIP amount every year is called step up sip
- Ultimately, the aim is to move towards a financial goal while using SIP investments
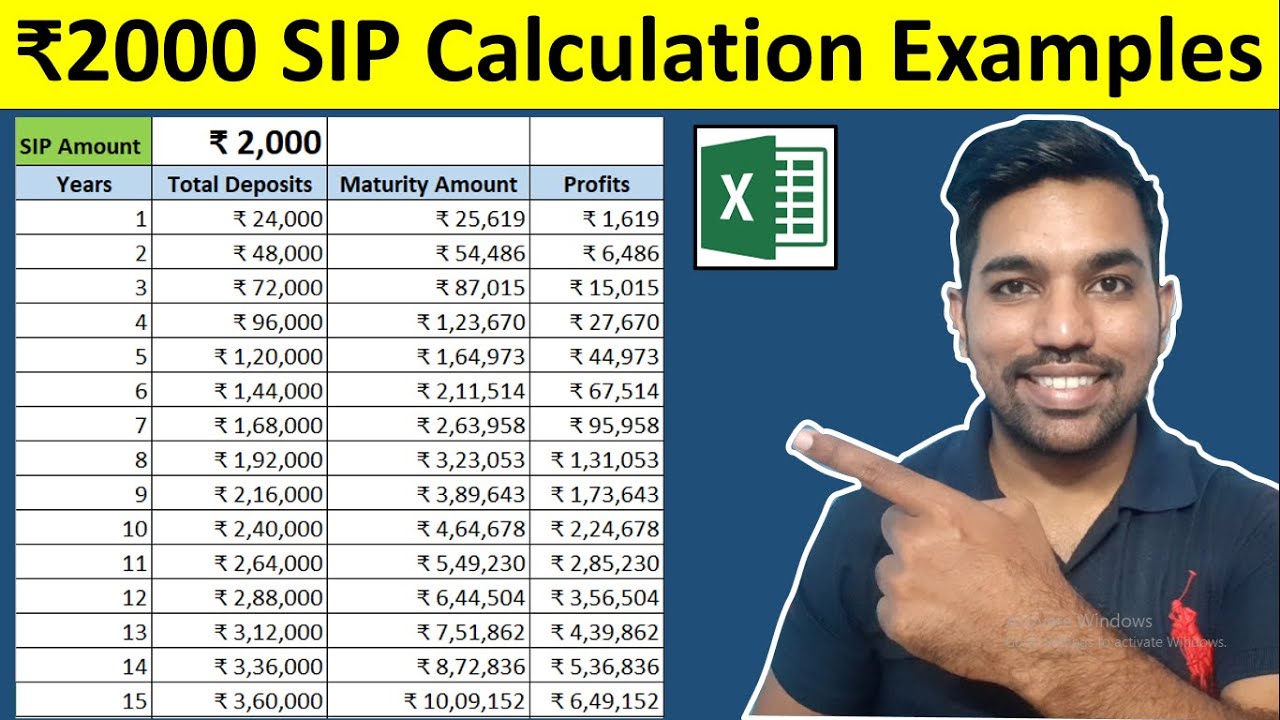
Rs. 2000 SIP Investment Returns Video
Watch more Videos on YouTube Channel
What is SWP?
- SWP full form is Systematic Withdrawal Plan
- It is a way to systematically withdraw from mutual funds every month to cover the expenses
- It is best known to withdraw only 4% of the investment amount every year to keep your money growing in mutual funds
- In order to start SWP, you need to have sufficient amount in mutual funds that can be accumulated via SIP or with lumpsum investment
- For example, if you have Rs. 1 crore in mutual funds and withdraw 4% (Rs. 4 lakh) every year, you’re taking out far less than the fund is expected to earn over the long term
- If the fund earns even 8% in a year (Rs. 8 lakh), your withdrawal of Rs. 4 lakh leaves the rest to keep growing your corpus
- Real returns aren’t steady, though. In a bad year your balance can dip, so a low withdrawal rate like 4% gives your corpus room to recover and is the main reason it’s the commonly suggested starting point
SWP for Monthly Income Video

SIP vs SWP Differences
Below are some differences between SIP vs SWP
| SIP | SWP |
|---|---|
| SIP full form is Systematic Investment Plan | SWP full form is Systematic Withdrawal Plan |
| It helps you to invests regularly | It helps you to withdraw regularly |
| SIP achieves financial goals from scratch (from ZERO investment) and increasing gradually | SWP needs good amount to be present in mutual funds for monthly income |
| The goals achieved with SIP can be buying a new house, car, children’s education, etc. | Goals achieved with SWP can be early retirement, covering monthly expenses based on income, passive income, etc. |
| SIP in ELSS mutual funds can save tax under Section 80C (Old Regime only, 3-year lock-in) | Only the profit portion of each withdrawal is taxed. For equity funds in FY 2025-26: 12.5% on long-term gains above Rs. 1.25 lakh a year, and 20% on short-term gains. See SWP monthly income taxation |
| Ideal stage: your earning years | Ideal stage: retirement or financial independence |
| Main risk: staying invested through market falls | Main risk: withdrawing too much, or selling units when markets are down |
SIP and SWP Together: A Real Example
Let’s say you start a SIP of Rs. 20,000 per month at age 35 and continue for 20 years, assuming a 12% expected annual return.
- Total invested: Rs. 48 lakh
- Approximate corpus at age 55: Rs. 2 crore
Now you switch to SWP and withdraw 4% of this corpus every year:
- Yearly withdrawal: Rs. 8 lakh
- Monthly income: about Rs. 66,667
Even if your fund earns only 8% after you retire, the corpus keeps growing because you’re withdrawing less than it earns. That’s the idea behind using SIP first and SWP later: the first builds the pot, the second turns it into a paycheck.
These figures are illustrations based on assumed returns. Actual mutual fund returns are not guaranteed and will vary.
Benefits of SIP
Below are some of the Benefits of SIP:
- Rupee Cost Averaging: SIP helps to invest regularly in mutual funds, which means, when market goes up you get less units and when market goes down you get more units
- Disciplined Investments: You regularly invest every month via SIP and hence your investments are disciplined
- Long term wealth creation: Using SIP, you can generate long term wealth since the value of mutual fund units appreciates over time
- Flexibility: You can start investing with as low as Rs. 500 every month via SIP to achieve your financial goals
Benefits of SWP
Let us now understand few benefits of SWP:
- Regular Monthly Income: You get monthly income regularly, based on the percentage of withdrawals using SWP
- Capital Preservation: Your investment amount and capital will be preserved over long term of at least 7 to 10 years, when you withdraw within 4% of your total investment amount
- Good for Retirees: SWP can help you get monthly income based on your investments, hence it is a good source of passive income to cover for monthly expenses
Which One Should You Choose?
It’s less “SIP vs SWP” and more “which stage are you in?”
| Your Situation | Better Fit |
|---|---|
| Salaried, in your 20s to 40s, building wealth | SIP |
| Have a lump sum but don’t need income yet | SIP or lump sum, SWP later |
| Retired or close to retirement with a decent corpus | SWP |
| Want to retire early (FIRE) | SIP now, SWP when your corpus can cover expenses |
| Need income but can’t handle market ups and downs | Neither alone. Consider safer options like SCSS or POMIS for part of your income |
If you’re already close to needing income, keep 1 to 2 years of expenses in a liquid or debt fund so you’re never forced to sell equity units during a market fall.
Conclusion
SIP and SWP aren’t rivals, they’re two stages of the same journey. If you’re getting started, SIP helps you build a strong corpus gradually. Once that corpus is large enough to cover your expenses, SWP lets you draw regular income from it while the rest stays invested.
The one rule to remember: keep your withdrawals comfortably below what your investments are likely to earn. You can test your own numbers with our SIP Calculator and SWP Calculator before you decide.
Frequently Asked Questions
Can I run SIP and SWP at the same time?
Yes, but usually in different funds. For example, you might withdraw from one fund via SWP for current expenses while continuing a SIP in another fund for long-term growth. Running both on the same fund just means you’re investing and withdrawing from the same pot.
Is SWP better than a monthly dividend option?
Generally yes. With SWP you decide the amount and timing, and only the gains portion is taxed. Dividends depend on the fund house, aren’t guaranteed, and are taxed at your slab rate.
Is SWP better than FD interest for monthly income?
It depends on your risk comfort. FD interest is predictable but fully taxable at your slab rate. SWP from an equity fund can grow your balance over time and is taxed only on gains, but it carries market risk.
How much corpus do I need to start SWP?
A common rule of thumb is about 25 times your yearly expenses, which corresponds to a 4% withdrawal rate. For example, if you need Rs. 6 lakh a year, a corpus of around Rs. 1.5 crore is a reasonable starting target.
Can I start SWP right after SIP?
Yes. There’s no waiting rule. Once your corpus is large enough to support your withdrawals, you can start SWP on the same fund and keep the rest invested.
Some more Reading:
Save Home Loan Interest Amount!
Use Home Loan Excel Calculator that will help you to Save Interest Amount on Home Loan EMI.
Click below button to download Home Loan EMI and Prepayment Calculator in Excel:
Watch how Home Loan Calculator in Excel Works
Income Tax Calculator App – FinCalC
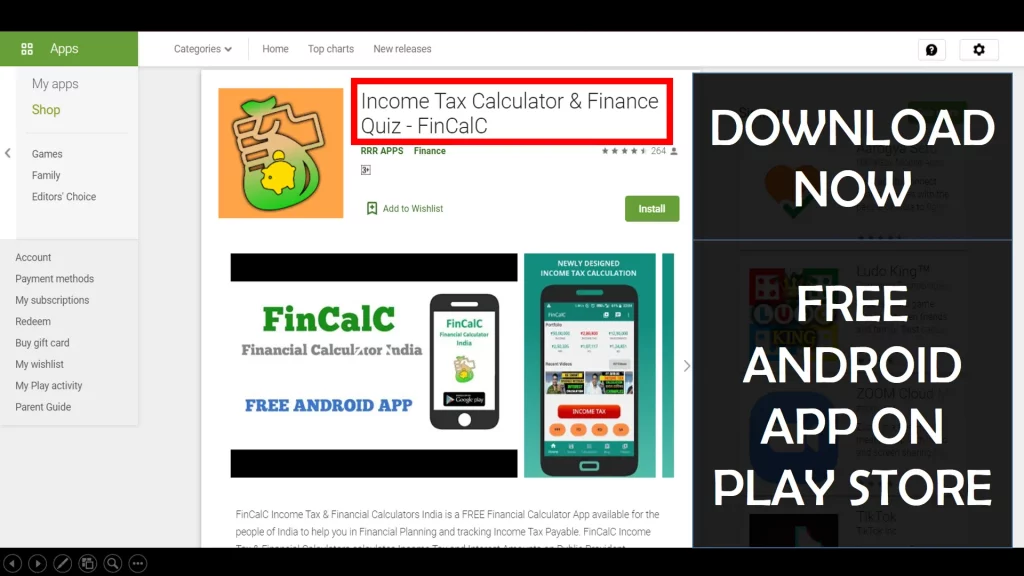
For Income Tax Calculation on your mobile device, you can Download my Android App “FinCalC” which I have developed for you to make your income tax calculation easy.
What you can do with this mobile App?
- Calculate Income Tax for FY 2026-27 and previous FY 2025-26
- Enter estimated Investments to check income tax with Old and New Tax Regime
- Save income tax details and track regularly
- Know how much to invest more to save income tax
- More calculators including PPF, SIP returns, Savings account interest and lot more
Use Popular Calculators:
- Income Tax Calculator
- Home Loan EMI Calculator
- SIP Calculator
- PPF Calculator
- HRA Calculator
- Step up SIP Calculator
- Savings Account Interest Calculator
- Lump sum Calculator
- FD Calculator
- RD Calculator
- Car Loan EMI Calculator
- Bike Loan EMI Calculator
- Sukanya Samriddhi Calculator
- Provident Fund Calculator
- Senior Citizen Savings Calculator
- NSC Calculator
- Monthly Income Scheme Calculator
- Mahila Samman Savings Calculator
- Systematic Withdrawal Calculator
- CAGR Calculator
I’d love to hear from you if you have any queries about Personal Finance and Money Management.
JOIN Telegram Group and stay updated with latest Personal Finance News and Topics.
Download our Free Android App – FinCalC to Calculate Income Tax and Interest on various small Saving Schemes in India including PPF, NSC, SIP and lot more.
Follow the Blog and Subscribe to YouTube Channel to stay updated about Personal Finance and Money Management topics.
Disclaimer: Mutual Fund investments are subject to market risks, read all scheme related documents carefully. Registration granted by AMFI, membership of SIRO (if applicable), and certification from NISM in no way guarantee performance of the intermediary or provide any assurance of returns to investors.
Distributor Details: Name: Abhilash Gupta | AMFI Registered Mutual Fund Distributor | ARN: 367014